Westpac Banking Joins Big Four Peers With Strict Crypto Payment Caps
This move raises immediate questions about how traditional banking infrastructure constrains legitimate retail adoption and exchange liquidity mechanisms.
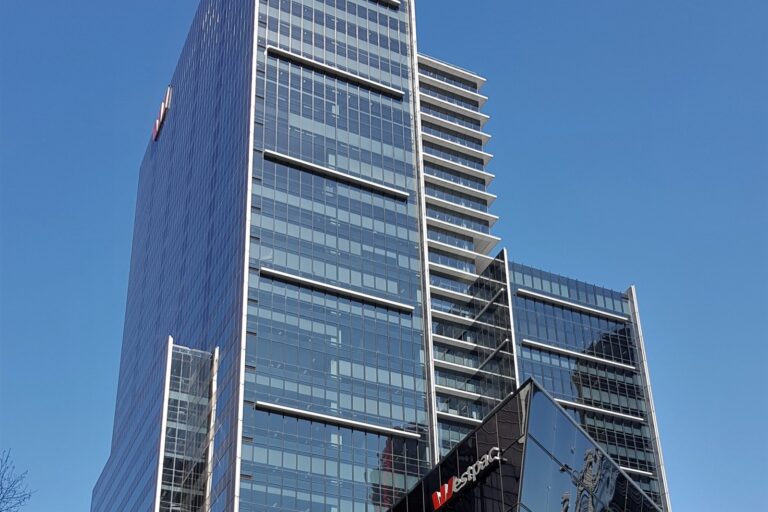
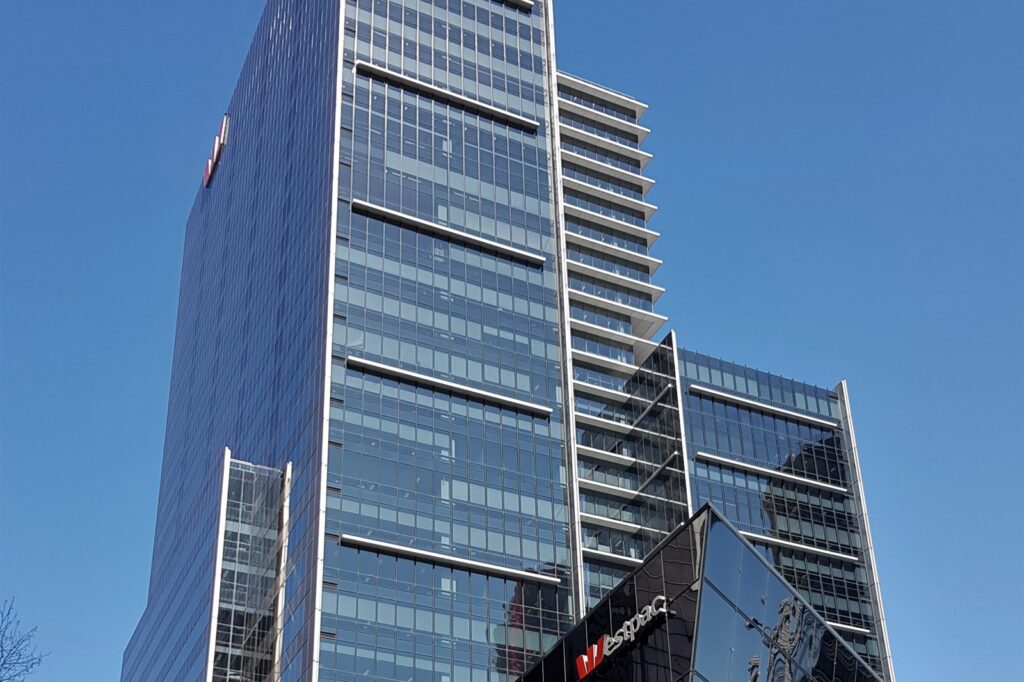
The bank is an Australian multinational financial services company headquartered at Westpac Place in Sydney. Established in 1817 as the Bank of New South Wales, it acquired the Commercial Bank of Australia in 1981 before being renamed to Westpac Banking Corporation in 1982. As of 2025, the institution serves 13 million customers worldwide and employs around 35,000 people.
The decision to cap payments follows a backdrop of anti-money laundering compliance and fraud prevention justifications common across the sector. Westpac remains one of Australia’s Big Four banks and holds the distinction of being Australia’s first and oldest banking institution. Its name is a portmanteau of “Western” and “Pacific”, reflecting its mission of becoming a significant Western Pacific bank.
Historical Context And Organizational Restructuring
The current operational environment at Westpac involves ongoing organisational reshaping and recent job cuts. The firm removed more than 250 roles since October 2026, a move that analysts suggest can affect cost efficiency and capital allocation. These structural changes occur against a history of significant corporate events dating back to the mid-1980s.
Subsequent significant events in the bank’s history include its involvement in the Gilbert and Ellice Islands, where Westpac formed the Bank of Kiribati as a joint venture in 1984. In 1985, Westpac replaced Barclays in the National Bank of Tuvalu, taking 40% of the shares and a management contract. By 1988, the firm had acquired operations in the Cook Islands and established branches in Fiji and Niue.
The bank faced its most severe financial challenge in 1992, when it recorded a loss of 1.6 billion dollars. This was the largest loss for an Australian corporation at the time and brought the firm close to insolvency. Consequently, Westpac slipped from being Australia’s largest bank to the third-largest. The company later sold its shares in the National Bank of Tuvalu in 1995 and acquired Challenge Bank that same year.
Investor Concerns Amidst Valuation Scrutiny
The stock last closed at A$37.21 with a total return of 109.1% over the past five years. Despite these gains, recent restructuring moves and regulatory scrutiny invite a fresh look at what investors are really paying for in terms of returns earned on capital. The issue now is whether the returns Westpac Banking earns on its capital are strong and durable enough to justify where the shares trade today.
The Excess Returns approach looks at how efficiently Westpac Banking turns its equity base into profit above the required return. On the model’s inputs, book value sits at about A$20.72 per share and is projected to edge up toward a stable A$21.71. Stable earnings are set at A$2.19 per share based on estimates from 12 analysts.
With an average return on equity of 10.07% and a cost of equity of A$1.74 per share, the framework points to an excess return of A$0.45 per share that needs to be weighed against the A$37.21 share price. A dividend cross check uses an annual payout of A$1.62 per share, a 73.41% payout ratio and implied dividend growth of about 2.56%, arriving at a present value output that sits modestly below where the stock trades today.
The Mechanics Of Transaction Limits And Liquidity
Westpac Banking has delivered strong share-price gains over the past five years, yet the latest restructuring moves and regulatory scrutiny invite a fresh look at what investors are really paying for in terms of the returns it earns on its capital. The catch is that job cuts and ongoing organisational reshaping can affect cost efficiency and capital allocation, which may influence how much return Westpac extracts from each dollar it invests in the business.
The mechanics here involve a direct trade-off between compliance overhead and service accessibility for retail clients.
This segmentation impacts exchange liquidity by forcing smaller traders to seek non-bank gateways. These alternative routes often come with higher fees or less regulatory protection, potentially increasing operational risk for the average user. The narrative suggests that rather than relying on a single multiple or model line item, each narrative lays out the key assumptions behind its view of fair value so you can compare those expectations with Westpac Banking’s actual results as they are reported.
Cryptocurrency In Full: Markets And Infrastructure
This post runs on cyberinktimes.com, which covers Cryptocurrency in full – markets, mining, scams, burnt and lost wallet recovery, KYC – plus internet and network infrastructure and data centers. The site maintains a tone that is calm, practical, and devoid of fear-mongering, focusing instead on factual analysis.
The audience includes readers interested in the full spectrum of digital assets, from market dynamics to the underlying infrastructure required to support them. Staying factual and sourced, every claim attributes its origin, ensuring no fabrication occurs even when discussing complex topics like regulatory caps or valuation models.
In summary, Westpac’s decision reflects a broader trend where traditional banking transaction limits act as a gatekeeper mechanism. The mechanics here reveal that while the bank maintains its capital efficiency through restructuring, the side effect is a reduction in accessible liquidity for retail crypto participants. As the industry evolves, the balance between regulatory compliance and market accessibility will likely remain a central tension.
Sources
- Westpac
- WestPAC Copper Division announces all-conference football honorees
- Westpac (ASX:WBC) Shares Could Be 15% Overvalued Following Job Cuts
Photo: J Bar (CC BY-SA 4.0)