
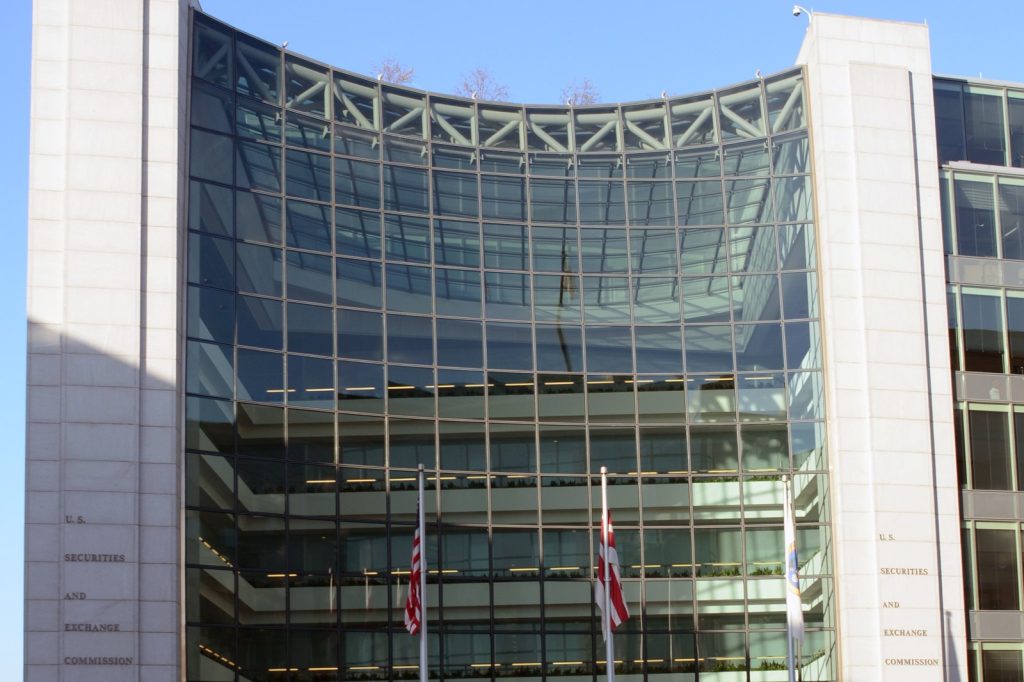
WASHINGTON, September 23 — The U.S. Securities and Exchange Commission proposed a new framework called Regulation Crypto Assets on August 18, 2026, according to a client memorandum from the law firm Skadden, Arps, Slate, Meagher & Flom LLP. The proposal would govern covered investment contracts involving a crypto asset that is not itself a security. If adopted, it would provide two fundraising pathways for issuers, and it also contemplates a safe harbor available to issuers whether or not they use a fundraising exemption.
That safe harbor would apply after an issuer has completed or permanently stopped the essential managerial work it had promised, is not making and does not intend to make new promises to perform such work, and has filed a required transition report explaining why and certifying that those conditions were met. The Skadden memo was authored by Alexander C.
Drylewski, Lara A. Flath, and Daley R. Epstein.
It warns that the proposal, if adopted in its current form, could create opportunities for private securities litigation on several fronts.
Where the litigation risk sits
The proposal expressly preserves private parties’ ability to argue that the crypto asset that is the subject of an offering remains tied to an investment contract or is otherwise a security after a transition report has been filed. Purchasers of that crypto asset after the transition report filing could potentially sue alleging their purchases were part of an unregistered offer and sale of securities under Section 12(a)(1) of the Securities Act of 1933.
In such a case, a court would independently apply the statutory text and the Howey test to determine whether the issuer actually completed or ceased all the essential managerial efforts it had promised. The transition report could strengthen an issuer’s defense, but it could also serve as evidence framing challenges over whether the issuer’s analysis matched its promises and actual conduct.
Because what constitutes essential managerial efforts is often a fact-intensive inquiry, it remains to be seen how such claims would play out in court. Private plaintiffs could also potentially bring claims for materially misleading statements or omissions in the issuer’s disclosure documents or transition report under Section 10(b) of the Securities Exchange Act of 1934 and Rule 10b-5.
A purchaser of a crypto asset under either pathway could allege, for example, that the issuer materially misstated a key aspect of its business plan, leadership, or plans and promises for the crypto project. Any plaintiff would still need to satisfy all other elements of a Section 10(b) claim, including reliance and causation.
Plaintiffs could also challenge the issuer’s transition report as materially misleading by alleging the issuer had not, in fact, completed or permanently ceased all the essential managerial efforts it previously represented or promised. Federal and state antifraud and antimanipulation rules would continue to apply.
What issuers should watch
The memo notes that, should the SEC’s proposal be adopted in its current form, companies looking to use the proposed exemptions or safe harbor may want to carefully address a number of important issues. The Skadden memorandum is provided for educational and informational purposes only and is not intended and should not be construed as legal advice; it is considered advertising under applicable state laws.
What comes next is whether the SEC adopts the framework as proposed or revises the transition-report and safe-harbor provisions that the memo identifies as the likeliest sources of future court fights.




