
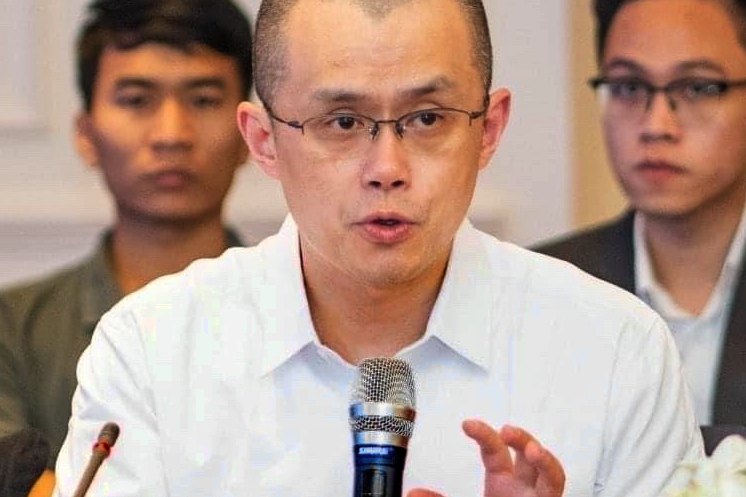
On November 26, 2023, Changpeng Zhao resigned as chief executive of Binance, the cryptocurrency exchange he co‑founded and grew into the world’s largest platform for digital assets. The departure follows fresh allegations from the U.S. Department of Justice that Zhao breached both the Bank Secrecy Act (BSA) and the International Emergency Economic Powers Act (IEEPA). The BSA obliges financial institutions to retain transaction records and file reports on suspicious activity, forming the core of U.S. anti‑money‑laundering enforcement.
IEEPA grants the president authority to regulate economic transactions during national emergencies, a tool frequently used to impose sanctions on countries such such as Iran and North Korea. The DOJ claims Zhao violated each of these statutes while operating Binance.
Zhao, a Canadian entrepreneur born in 1977, previously served as chief technology officer at OKCoin before launching Binance. Under his leadership, the exchange expanded rapidly, offering spot trading, futures, staking, launchpads and a host of other services to a global clientele. That worldwide reach, however, attracted regulatory scrutiny.
Authorities in several jurisdictions questioned Binance’s lack of a fixed headquarters and its willingness to serve users in regions where it held no license, with the United States presenting the most consequential challenge. The timing of Zhao’s resignation suggests a direct response to the DOJ investigation.
When a CEO steps aside amid a federal probe into potential anti‑money‑laundering and sanctions violations, the move is rarely voluntary; it is commonly interpreted as a strategic concession aimed at insulating the company from further legal exposure. Binance’s board appears intent on distancing the firm from its founder as it navigates the mounting pressure. The allegations carry significant weight. A violation of the BSA could expose Binance to fines running into the hundreds of millions, or even billions, of dollars.
IEEPA violations, which relate to the facilitation of prohibited sanctions‑targeted transactions, also invite severe penalties and may lead to criminal charges against individuals involved. While Zhao’s exact net worth is not publicly disclosed, it is reasonable to assume that a substantial portion of his assets is now tied up in legal costs and potential settlements.
For the broader crypto industry, the case marks a sobering reminder that size does not confer immunity from U.S. financial law. Binance, long viewed as the “too‑big‑to‑fail” exchange, was emblematic of a libertarian‑tech founder narrative that positioned the platform outside traditional regulatory frameworks. The DOJ’s action signals a shift toward stricter enforcement of anti‑money‑laundering and sanctions rules across the sector.
Other digital‑asset platforms are reportedly reassessing their compliance programs, reviewing exposure to sanctioned entities, and evaluating how they serve U.S. customers. Binance now faces the task of appointing a new chief executive capable of steering the firm through ongoing legal battles and rebuilding relationships with regulators.
Despite the leadership change, Binance continues to offer deep liquidity and a breadth of products that few competitors can match, suggesting that an immediate exodus of users is unlikely. Nevertheless, trust—an essential component of any financial service—has been eroded. Restoring confidence will require sustained compliance efforts and transparent engagement with authorities.
Zhao’s exit closes a defining chapter of the cryptocurrency boom, but it also inaugurates a legal process that will shape Binance’s future and potentially set new precedents for how crypto exchanges operate under U.S. law.




